Regulating Insurance in the Dark
State Insurance Commissioners and the Fight for Homeowners Insurance Data Transparency
By Rick Morris
Executive Summary
In July 2026, Public Citizen surveyed state insurance commissioners regarding a June 2026 initiative to collect data from insurers on homeowners insurance (known as a “data call”), including information on premiums and nonrenewals.[1] Commissioners should not only collect this information so they can regulate the industry effectively but, amid a growing climate-driven insurance crisis, make the data public to promote competition among insurers and enable the public and policymakers to oversee the industry and its regulators. Public Citizen’s key findings are as follows:
- Most insurance commissioners’ offices did not respond to multiple inquiries about the homeowners market data call.
- Of those who did respond, most are participating in the data call.
- Too often, whether the public will be able to see a state’s data depends on staff capacity and the whims of individual insurance commissioners.
- Without public access to this data, markets can neither be considered competitive, nor provide meaningful signals about climate risk.
America’s home insurance crisis is also an information crisis. Homeowners and renters are burdened by rising premiums, shrinking coverage options, and slower and stingier resolution of claims. Although the insurance industry argues that competitive markets and price signals give consumers information they need to make informed decisions, much of the most basic information about homeowners insurance markets is not readily available to the public or even regulators themselves.
Public Citizen surveyed all 56 state and territorial insurance commissioners about their participation in the 2026 homeowners market data call and their plans to make the resulting information publicly available at the ZIP-code level. Twenty-three offices responded in some fashion: 18 answered our questions and 5 responded to our outreach without addressing the questions. Among the 18 offices that answered the questions, 78%—14 offices—affirmed that they were participating in the homeowners market data call. However, since over half of the insurance offices did not respond, we cannot be sure how many states are participating.
However, participation in data collection does not necessarily mean a commitment to transparency. While 28% of responding offices said they support publication of homeowners insurance data at the ZIP-code level, 56% did not directly answer the question and another 17% gave conditional answers tied to the National Association of Insurance Commissioners’ (NAIC) forthcoming recommendations. In other words, most insurance commissioners who responded to our survey were unwilling to say whether they believe the public should have access to granular information about their own insurance markets.
Some states already make varying categories of ZIP-code-level information publicly available. Others deferred the question to the NAIC, and still others have no plans to publish this data. This fragmented landscape means that the amount of information available to a consumer too often depends solely on the whim of their insurance commissioner. It also makes it more difficult to compare insurance markets across state lines, identify regional trends, and determine whether insurers are providing consumers with meaningful choices.
Dramatically unequal staffing and resources are available to state and territorial insurance departments. When some regulators oversee thousands of insurers with only a handful of staff, transparency cannot depend entirely on the resources of individual insurance departments.
Competition is supposed to be a central pillar of insurance regulation. The NAIC itself describes its mission as ensuring “fair, competitive, and healthy insurance markets to protect consumers.” But when consumers cannot meaningfully compare insurance companies’ premiums, claims and denials, nonrenewals, and other basic information, insurance companies cannot be meaningfully said to be competing for their business.
In order to overcome disparities of staff capacity and ensure foster more competitive state insurance markets, state insurance regulators and the NAIC should work together to maintain a standardized publicly accessible national dataset.
At a minimum, regulators should publish data on average premiums, losses, deductibles, nonrenewal notices, and mitigation discounts by year, ZIP code, and policy type; update the information regularly; and formally recognize consumer access to market information as a fundamental component of a competitive insurance market, as well as a critical tool for the public and policymakers to oversee insurers and insurance regulators.
Introduction: The Opaque Home Insurance Crisis
The homeowners insurance crisis is also an information crisis.
If you live in the United States, you’ve almost certainly seen your housing costs dramatically rise over the last several years and had a harder time finding home insurance.[2] If you filed a claim, you were almost as likely to see it denied as paid,[3] and if it was paid, then there is a strong chance it was delayed[4] or underpaid.[5]
Property and casualty insurance companies blame climate-driven extreme weather for rising prices and falling quality. While such disasters are certainly part of the problem, Public Citizen, partner organizations, and independent ratings agencies have reported on the industry’s historic profits,[6] historic executive compensation,[7] billion-dollar advertising wars,[8] and regulatory capture[9] that most certainly also contribute to soaring rates.
The insurance industry claims that its competitive marketplace and price signals provide consumers valuable information about where to live and which policies to purchase in order to minimize their risks, minimize their costs, and maximize the value they receive from their property insurance.
However the public, researchers, and regulators themselves were blind[10] to how the most basic insurance metrics varied from place to place until late 2024 and early 2025, when data released by Treasury’s Federal Insurance Office (FIO)[11] and the Senate Budget Committee (SBC)[12] provided a long-awaited window into the insurance crisis.[13] That data call proceeded despite the intense opposition of more than half of state insurance commissioners.[14] In 2024, as part of the effort to oppose FIO’s collection and release of data, the NAIC recommended state commissioners conduct their own data calls on the homeowners market in 2024. In 2025, it again recommended a state data call which then began in March of 2026.[15]
Methodology
In early July 2026, just ahead of the states’ data collection deadline, Public Citizen contacted all 56 state and territorial insurance commissioners/offices.
We used the state insurance commissioner tracker maintained by the Revolving Door Project to find contact information for all insurance commissioners.[16] The NAIC does not maintain a complete public list of insurance commissioner contacts, and some insurance commissioner offices do not provide contact information.
Our outreach included an initial email, three follow-up emails, and attempted phone contact. When we received out of office messages, bounced emails, or were redirected to other state offices, we followed up with different staff members’ emails, a phone call, and reached out after the date indicated by the out of office messages.
We asked each insurance commissioner the following three questions:
- Is your department participating in the NAIC’s ongoing homeowners market data call?
- Does your department support the NAIC publishing homeowners market data at the ZIP-code level?
- Does your department plan to publish ZIP-code-level homeowners market data for your state or territory, regardless of whether the NAIC publishes it nationally?
We then categorized the commissioners’ responses to each question as follows:
- Yes: The office responded affirmatively.
- Maybe: The office provided a conditional response or its position remains uncertain.
- No Response: The office did not answer the question.
As a number of commissioners replied in some way to our outreach, but did not answer any questions, we categorized the commissioners’ reply to our outreach as follows:
- Yes: The office responded to at least one question.
- Inconclusive: The office responded to our outreach, but did not address any of our questions.
- No: The office did not respond to our outreach.
Findings
Of the 56 state and territorial insurance commissioners we surveyed, 23 responded in some way. Of those, 5 offices replied to our emails but did not address the questions and 18 responded to our inquiries. Their responses are summarized in the table below.
Table 1: Summary of Insurance Commissioner Responses
| State/Territory | Commissioner | Replied | Q1: Participating? | Q2: Supports the NAIC publishing zip-code level data? | Q3: Plans to publish state zip-code level data? |
| Arizona | Director Charles “Chuck” Bassett | Yes | Yes | No Response | No Response |
| Colorado | Commissioner Michael Conway | Yes | Yes | No Response | Maybe |
| Connecticut | Commissioner Joshua Hershman | Yes | Yes | Yes | Yes |
| District of Columbia | Commissioner Karima Woods | Yes | Yes | No Response | Yes |
| Guam | Commissioner Michelle B. Santos | Yes | No | Yes | No |
| Iowa | Commissioner Doug Ommen | Yes | Maybe | No Response | No Response |
| Kentucky | Commissioner Sharon Clark | Yes | No Response | No Response | No Response |
| Maryland | Commissioner Marie Grant | Yes | Yes | No Response | No Response |
| Massachusetts | Commissioner Michael Caljouw | Yes | Yes | No Response | Yes |
| Minnesota | Commissioner Grace Arnold | Yes | Yes | Maybe | Maybe |
| Mississippi | Commissioner Mike Chaney | Yes | Yes | Yes | Yes |
| Missouri | Director Angela Nelson | Yes | Yes | Maybe | Maybe |
| New Mexico | Superintendent Alice Kane | Yes | Yes | Yes | No |
| North Dakota | Commissioner Jon Godfread | Yes | Yes | Maybe | Maybe |
| Ohio | Director Judith French | Yes | No Response | No Response | No Response |
| Pennsylvania | Commissioner Michael Humphreys | Yes | Yes | No Response | No Response |
| Texas | Commissioner Amanda Crawford | Yes | Yes | Yes | Yes |
| Vermont | Commissioner Kaj Samson | Yes | Yes | No Response | No Response |
| Illinois | Director Ann Gillespie | Inconclusive | |||
| Indiana | Commissioner Holly Lambert | Inconclusive | |||
| Nevada | Commissioner Ned Gaines | Inconclusive | |||
| Oregon | Commissioner TK Keen | Inconclusive | |||
| Puerto Rico | Commissioner Suzette M. Del Valle | Inconclusive | |||
| Alabama | Commissioner Mark Fowler | No | |||
| Alaska | Director Heather Carpenter | No | |||
| American Samoa | Commissioner Peter Fuimaono | No | |||
| Arkansas | Commissioner Jimmy Harris | No | |||
| California | Commissioner Ricardo Lara | No | |||
| Delaware | Commissioner Trinidad Navarro | No | |||
| Florida | Commissioner Michael Yaworsky | No | |||
| Georgia | Commissioner John King | No | |||
| Hawaii | Commissioner Scott Saiki | No | |||
| Idaho | Director Dean Cameron | No | |||
| Kansas | Commissioner Vicki Schmidt | No | |||
| Louisiana | Commissioner Tim Temple | No | |||
| Maine | Superintendent Robert Carey | No | |||
| Michigan | Commissioner Anita Fox | No | |||
| Montana | Commissioner James Brown | No | |||
| Nebraska | Director Eric Dunning | No | |||
| New Hampshire | Commissioner D.J. Bettencourt | No | |||
| New Jersey | Commissioner Susan Ochs | No | |||
| New York | Superintendent Kaitlin Asrow | No | |||
| North Carolina | Commissioner Mike Causey | No | |||
| Northern Mariana Islands | Secretary Remedio C. Mafnas | No | |||
| Oklahoma | Commissioner Glen Mulready | No | |||
| Rhode Island | Superintendent Elizabeth Dwyer | No | |||
| South Carolina | Director Michael Wise | No | |||
| South Dakota | Director Larry Deiter | No | |||
| Tennessee | Commissioner Carter Lawrence | No | |||
| U.S. Virgin Islands | Lieutenant Governor Tregenza Roach | No | |||
| Utah | Commissioner Jon Pike | No | |||
| Virginia | Commissioner Scott White | No | |||
| Washington | Commissioner Patty Kuderer | No | |||
| West Virginia | Commissioner Erin Hunter | No | |||
| Wisconsin | Commissioner Nathan Houdek | No | |||
| Wyoming | Commissioner Jeff Rude | No |
Finding One: Most Commissioners Who Answered the Survey Are Participating.
Among offices that answered question 1, 78% (14 out of 18) affirmed that they are participating in the homeowners market data call.
Finding Two: Capacity Challenges Limit Participation and Oversight.
The Guam Insurance Commissioner Michelle B. Santos stands out as the singular respondent who is not participating in the homeowners market data call. While Commissioner Santos responded that she would like to participate in the data call and supports the NAIC publishing zip-code level data, she stated that her office’s limited capacity prevents their participation.
1. Is your department participating in the NAIC’s ongoing homeowners market data call?
“No. We are short handed with staff and cannot do so at this time.”
-Guam Insurance Commissioner Michelle B. Santos
Commissioner Santos’s predicament reflects a broader problem of insurance commissioner office capacity documented by the Revolving Door Project.
Kenny Stancil, deputy research director at the Revolving Door Project, notes,
Staffing and budgets also vary between [state insurance commissioner] jurisdictions. This is a key issue because without sufficient resources, it’s impossible for state-level insurance offices to adequately oversee the powerful financial institutions they’ve been tasked with regulating.[17]
Research conducted by the Revolving Door Project shows that state insurance departments have dramatically different staffing levels and regulatory capacities. California employs 1,398 department staff who regulate 1,441 insurance companies, a near 1:1 ratio, while Wyoming’s 26 insurance department staff are responsible for overseeing 1,485 insurance companies.
In a decentralized regulatory system wherein each state and territory is responsible for overseeing and reporting on its own insurance market, uneven regulatory capacity makes nationwide insurance data transparency even more important. A regulator with limited staff may struggle to collect, analyze, and publish market data even when it recognizes the value of doing so. Public access to standardized, granular data can help compensate for these uneven resources by allowing consumers, researchers, journalists, and policymakers to independently assess insurance markets. When regulatory capacity varies dramatically from one jurisdiction to another, transparency should not depend solely on the resources of individual insurance departments.
Finding Three: Most Regulators Are Unwilling to Talk About Transparency
A striking contrast emerged in the insurance commissioners’ responses. While 78% said their states will participate in the data call, their commitment to data transparency was much less clear.
Most respondents did not directly answer Question 2: “Does your department support the NAIC publishing homeowners market data at the ZIP-code level?”
While some (28%) of respondents replied that they supported the NAIC publishing zip-code level data, most offices either did not address the question (56%), or replied that their support depended on the NAIC’s forthcoming recommendations (17%).
The Arizona Department of Insurance was one of several offices that said it preferred to keep the data confidential. This stance echoes how the insurance industry consistently uses a “trade secrets” defense against demands for information.
Replies from Kentucky and Missouri illustrate a divide in the level of deference the commissioners give to the NAIC. Kentucky Commissioner Clark’s brief response directing us to the NAIC was echoed by several offices. On the other hand, several offices responded similarly to Missouri Commissioner Nelson, who asserted state sovereignty over the NAIC and the data call.
“. . .[T]he questions appear to assume that the data call is being initiated by the NAIC. I want to clarify that this data call is a collaborative effort among states, facilitated by the NAIC. But, at least as to specific Missouri data, the data call was initiated by and is being conducted under Missouri law and the responsive data will be handled accordingly.”
-Missouri Insurance Commissioner Angela Nelson
2. Do you support the NAIC publishing zip-code level data?
“I will refer you to the NAIC Homeowners Market Report Working Group for any questions on this issue.”
-Kentucky Insurance Commissioner Sharon Clark
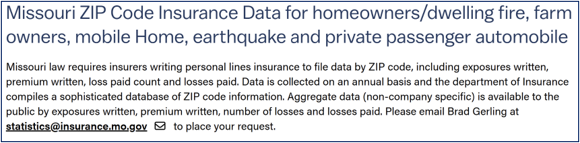
States such as Missouri that make zip-code level data available upon request, as opposed to publishing it affirmatively, create a serious hurdle for consumer understanding of their state insurance markets.
In these states, the insurance commissioner acts as a gatekeeper of information the public needs to navigate an opaque and confusing industry, and researchers, lawmakers, and advocates need to understand trends in the market.
On the other hand, states such as Connecticut, the insurance capital of the country, Mississippi, and Texas offered full throated support for national data transparency.
Texas’s position represents a tide shift from one insurance commissioner’s tenure to the next. The former commissioner lobbied against[18] and refused to participate[19] in the previous data call. Under the current commissioner, Texas publishes homeowners insurance information through a user-friendly interactive map at the county-level of granularity.[20]
Similarly, Massachusetts has published much of the data currently being collected at the zip-code level for decades.[21]
These states prove that collecting and publishing such information is possible, but that the decision is often left to the whim of an individual state regulator.
Finding Four: Most Consumers Are Left in the Dark.
Consumers have vastly different access to information depending on where they live in the country. If someone in Texas wanted to move to where the insurance market was safest, with the lowest average premiums and fewest nonrenewals, they could easily refer to the state’s insurance map. Someone in Massachusetts could find similar information, but they would have to wade through a few hundred pages of the Statistical Supplement to the Annual Home Insurance Report to do so.
Meanwhile, in most of the country, consumers have little to no access to such information outside of the (already outdated) few years of data captured and published by FIO and SBC, and which was subsequently mapped by Public Citizen and the Revolving Door Project.[22]
As a result, most people cannot use property insurance data to inform their decisions about where to live to minimize the risks they face or the costs they incur.
Finding Five: The Uneven Regulatory Landscape Fosters Regulatory Arbitrage.
Such an uneven regulatory landscape provides opportunity for regulatory arbitrage. Anecdotally, legislators and insurance commissioners in numerous states have told Public Citizen that insurance companies have threatened to abandon their states if policymakers impose new rules. Insurance insiders confirm this activity, as Chris Tobe, a public pension investment consultant and former insurance company executive told NBC News,
Insurance companies don’t simply compete for customers—they compete for regulators. When management decided where to domicile a new insurance company, one of the first questions was not, “Which state has the toughest consumer protections?” Instead, it was, “Which state offers the most favorable regulatory environment?”[23]
As a result of this competition for weak regulation instead of the best service to consumers, 16 states lack even some basic consumer protections such as the NAIC’s Unfair Property/Casualty Claims Settlement Practices Model Regulation.[24] When consumers face different basic definitions of fairness across state insurance markets, the industry enjoys a race to the bottom of what it is expected to pay out when disaster strikes. This phenomenon has been described at length by legal scholar Jay M. Feinmann in his definitive book, Delay Deny Defend: Why Insurance Companies Don’t Pay Claims and What You Can Do About It.
Ratings agencies and the industry’s financials confirm Feinmann’s thesis. Weiss Ratings, the nation’s only independent insurance company rating agency, revealed that in 2024, 13 large U.S. property insurers flatly denied 40% to 70% of the 3.9 million homeowner claims from the previous year.[25]
The trend has continued, with Weiss reporting that “15 large U.S. insurers, including State Farm of Florida and other State Farm subsidiaries, flat-out denied at least 50% of homeowner and farmowner claims in 2025.”[26] The reason for such delays and denials is plain: for just a single day of merely delayed claims, homeowners insurance companies collectively take in an extra $8.8 million in interest and investment income.[27] Due in no small part to these practices, the industry’s investment and underwriting profits have surged to historic highs in recent years.[28]
It looks like the property and casualty industry may have overplayed its hand of late. In just this current year, the California Department of Insurance is poised to issue the highest penalty in its history against State Farm for its treatment of survivors of the 2025 Los Angeles Wildfires;[29] the Oklahoma Attorney General has sued State Farm and Allstate for unjustly denying or underpaying wind- and hail-related claims in systematic racketeering schemes engineered to defraud policyholders whose roofs were damaged during severe storms;[30] and a class action and racketeering lawsuit is being investigated by the American Policy Holders Institute against the Texas Windstorm Insurance Association, the insurer of last resort composed of every traditional private property insurer in the state.[31]
An opaque and fragmented market is a market in which fraud is only a matter of time.
Finding Six: Data Silos Impede Consumer Protection.
While insurance is regulated at the state level, climate-driven extreme weather disasters and property insurance disruptions don’t stop at state borders, and trends cannot be identified with a one time exercise.
This fragmented data environment makes it difficult to identify regional patterns, affordability trends, geographic disparities, and illegal cross-state market subsidization (that is, consumers in low regulation states subsidizing consumers in high regulation states). In an attempt to protect the residents of Illinois, Attorney General Kwame Raoul is suing State Farm in order to uncover the very information inquired about by this survey and which is required to be disclosed by state law.[32]
Finding Seven: Most States Have a De Facto Noncompetitive Home Insurance Market.
This lack of transparent and accessible data undermines the basis of insurance regulation: that a competitive state insurance market is the principle foundation of consumer protections and the most important concern for state regulators.
It is worth quoting the opening sentences of the NAIC’s mission statement in full:
Our members are state insurance regulators from diverse backgrounds—but are united in their shared commitment to set standards and ensure fair, competitive, and healthy insurance markets to protect consumers. The singular mission of the NAIC is to support our members in these noble causes. [Emphasis added].
Consumers in the vast majority of states lack basic information about insurance premiums and nonrenewals by zip-code, let alone by company. In some states, statistics about the largest insurers may be available, as they are in Massachusetts, where a resident can find the total premium written, total loss, and cancellation/nonrenewal history of the top 25 insurers.[33]
When consumers lack basic information by which to compare insurers, insurance companies are not forced to compete properly. What could those companies possibly be competing on? What incentive does an insurer have to reduce premiums, discount home and community resilience improvements, pay claims more quickly and reliably, or even provide responsive service when a consumer has no way of knowing the insurer does these things and can’t see whether it compares favorably to other companies?
When consumers lack information to allow them to make an educated choice between insurance companies, a state insurance market cannot be adequately competitive. Such a lack of consumer information in the majority of states indicates that many insurance commissioner offices have failed at their self-described primary job for decades.
Policy Recommendations
The United States Needs Ongoing, Granular, and Publicly Accessible Homeowners Insurance Data.
State insurance regulators and the NAIC can take steps to ameliorate opaque and noncompetitive markets by doing the following:
- Publish homeowners insurance average premiums, losses, deductibles, nonrenewal notices and mitigation discounts by year, ZIP code and policy type (home, renter, condominium or mobile home).
- Update the data regularly rather than treating each data call as a one-time exercise.
- Fix the regulators’ capacity limitations by increasing industry fees to cover adequate oversight, working with partner states with large enough offices to share capacity, or creating a capacity-sharing mechanism through the NAIC.
- Create pathways for public access to insurance regulators beyond consumer complaints at state insurance offices and the NAIC’s consumer representative role. People should have access to their state regulator, especially as rates climb and coverage dwindles.
- Define a competitive state insurance market to include consumer access to information on average premiums, losses, deductibles, nonrenewal notices and mitigation discounts by year, ZIP code and policy type (home, renter, condominium or mobile home).
Conclusion: The Public Has a Right to See the Market.
Ongoing, granular, and publicly accessible information can help homeowners and renters by making insurance companies compete for their business, by informing their decisions about where to live, and by allowing regulators, lawmakers, academics, and consumer advocates to work on their behalf.
Without access to such information, consumers are left vulnerable to being grossly overcharged[34] while valid claims are delayed, denied, and underpaid—all while property and casualty insurers enjoy historic profits, funnel our money to CEOs and shareholders,[35] and engage in billion-dollar advertising wars.[36]
The whims of individual state insurance commissioners should not determine whether critical information is accessible to the public or is even collected at all. Among the subset of insurance commissioners who responded to our survey, the majority are collecting this information. But it remains to be seen whether their peers are participating in the data call, whether insurance commissioners themselves will be able to see the data from beyond their own states’ borders, and to what extent the rest of us will be able to access the information.
Consumers should not have to rely on industry talking points, anecdotes, incomplete data, or advertising mascots to compare companies and to understand whether insurance markets are functioning in their states. If regulators believe that competition protects consumers, they should provide their states’ consumers the information necessary to make informed choices. The public cannot trust an insurance market that it is not allowed to see.
Endnotes:
[1] https://content.naic.org/industry/data-call/property-ho.htm
[2]https://content.naic.org/article/naic-releases-first-its-kind-national-analysis-homeowners-insurance-market-trends “Average premium per policy increased across every NAIC region since 2018, with inflation-adjusted increases ranging from 18.3% to 43.3%.” Notably, these figures are only for those who can still find coverage in the traditional market. The NAIC also reports that “during the same period, company-initiated non-renewal rates increased between 96% and 216%.” Those homeowners may have then either gone without insurance, as is the case for many lower income heirs property owners, or turned to state administered FAIR plans which provide more limited coverage at even higher costs in the 33 states and District of Columbia which offer them.
[3] https://weissratings.com/en/weiss-news/14-large-u-s-insurers-closed-nearly-half-of-homeowner-claims-with-no-payment-in-2024
[4]https://consumerfed.org/news/press-releases/new-analysis-homeowners-insurance-companies-earn-millions-in-interest-and-investment-income-with-every-day-of-claim-delay/
[5]https://cdn−order.weissratings.com/media/wri/PDF/WN/SixSneakyTacticsHomeInsurersAreUsingtoStiffConsumers.pdf See “Sneaky Tactic #3 Cutting Claims to the Bone” on pp. 6-9.
[6] https://www.citizen.org/article/insurers-score-record-profits-while-consumers-pay/
[7] https://www.citizen.org/article/insurers-score-record-profits-while-consumers-pay/
[8]https://www.spglobal.com/market-intelligence/en/news-insights/articles/2025/3/progressives-advertising-expenditure-hits-record-high-in-2024-88020488
[9] https://insurancenewsnet.com/innarticle/switching-sides-many-ex-insurance-commissioners-go-straight-to-industry-roles
[10] https://scholarship.law.umn.edu/cgi/viewcontent.cgi?article=1582&context=faculty_articles
[11] https://home.treasury.gov/news/press-releases/jy2791
[12]https://www.budget.senate.gov/chairman/newsroom/press/budget-committee-releases-sweeping-new-report-highlighting-economic-budgetary-costs-of-climate-change
[13] https://www.citizen.org/article/mapping-the-home-insurance-crisis/
[14] https://therevolvingdoorproject.org/mapping-the-home-insurance-crisis-anti-fio-states/
[15] https://content.naic.org/industry/data-call/property-ho.htm
[16] https://therevolvingdoorproject.org/tracking-state-insurance-commissioners/
[17] https://therevolvingdoorproject.org/mapping-home-insurance-regulation/
[18] https://therevolvingdoorproject.org/mapping-the-home-insurance-crisis-anti-fio-states/
[19] https://www.nytimes.com/interactive/2025/01/16/climate/home-insurance-cancellations.html
[20] https://www.tdi.texas.gov/general/texas-homeowners-insurance-market-overview.html
[21] https://www.mass.gov/info-details/the-commissioners-report-on-home-insurance
[22] See: https://www.citizen.org/article/mapping-the-home-insurance-crisis/
[23]https://www.nbcnews.com/business/business-news/21-billion-problem-regulators-missed-mark-walters-insurance-empire-rcna595774
[24] See the model regulation here: https://content.naic.org/sites/default/files/model-law-902.pdf States that lack this regulation: CT, HI, ID, IN, IA, ME, MA, MI, MS, MT, NM, ND, SD, SC, WI, WY. (Unpublished research from Americans For Financial Reform, courtesy of Alex Martin.)
[25]https://weissratings.com/en/weiss-ratings-daily/homeowners-beware-big-insurers-deny-half-of-damage-claims
[26]https://weissratings.com/en/weiss-news/15-large-u-s-insurers-denied-more-than-half-of-homeowner-claims-in-2025
[27] https://consumerfed.org/news/press-releases/new-analysis-homeowners-insurance-companies-earn-millions-in-interest-and-investment-income-with-every-day-of-claim-delay/
[28] https://www.citizen.org/article/insurers-score-record-profits-while-consumers-pay/
[29] https://www.insurance.ca.gov/0400-news/0100-press-releases/2026/release019-2026.cfm
[30] https://prospect.org/2026/08/26/cracking-down-on-big-insurance-in-oklahoma/
[31]https://www.houstonchronicle.com/politics/texas/article/twia-hurricane-beryl-lawsuit-22393410.php
[32]https://illinoisattorneygeneral.gov/news/story/attorney-general-raoul-sues-to-force-state-farm-to-turn-over-homeowners-insurance-data-to-illinois-department-of-insurance
[33]https://www.mass.gov/doc/statistical-supplement-to-the-massachusetts-market-for-home-insurance-2024/download
[34]https://apnews.com/article/insurance-regulations-housing-costs-trump-affordability-0b70d9a4131a0772f2771b155400cd5a
[35] https://www.citizen.org/article/home-insurance-executives-are-raking-it-in-at-your-expense/
[36] https://revolvingdoorproject.substack.com/p/dont-let-home-insurers-fool-you-theyre